


I’m not a huge fan of macroeconomics when it comes to investing.
Don’t get me wrong—I love macroeconomics as a subject. It’s fascinating, incredibly insightful, and let's be honest, living in a capitalist system means understanding macro is key to grasping how the world operates. But when it comes specifically to investing, I try to steer clear of macro-driven decisions as much as possible.
Why?
Because I’ve seen far too many investors jump in and out of positions based solely on macroeconomic events—even when the companies they own are operationally unaffected.
Take Sarah, for example. She sold her shares in a profitable cloud software company when interest rate expectations started climbing. The company had barely any debt, was generating cash hand over fist, yet Sarah panicked simply because the entire tech sector was dipping. Fast forward a year, and that same stock had rallied 40%.
I firmly believe that long-term investing inevitably means weathering storms of both prosperity and hardship. That's precisely why I prefer to zero in on company-specific factors.
And yet, here we are today, diving deep into macroeconomic factors. Why the sudden shift?
Because this is Part II of our deep dive into Aris Water Solutions (I’ll call it Aris rather than AWS because, honestly, I don’t need Amazon's legal team knocking on my door). If you've read Part I, you already know Aris provides water services primarily to oil and gas companies in the Permian Basin, operating a full-cycle water management system—collecting, treating, recycling, and disposing of wastewater produced during extraction.
During my research into Aris, I quickly realized that ignoring macroeconomic factors this time around just wasn’t possible. So today, we're exploring external influences—not just oil prices and inflation, but also regulation and geology, which can either boost or derail Aris’s business.
We've got plenty to unpack, so let's dive in!
Back to Basics
Let's kick things off with broader macroeconomic factors like interest rates and inflation since they're probably familiar territory for most of you.
Interest rates have a pretty limited impact on Aris’s business. According to management's latest 10-K filing, a 1% rise in interest rates would add just $0.4 million in extra financing costs. Considering Aris has around $25 million in profit in 2024, this isn’t exactly something to lose sleep over.
Inflation, however, could significantly impact Aris, especially considering potential tariffs proposed by Trump. Aris works with fixed-term contracts for water treatment and recycling (more on that in upcoming parts). While these contracts are inflation-protected, there's a cap. Meaning, if inflation exceeds this cap, Aris can't fully pass along increased costs to its customers. So, if you're thinking about investing in Aris, keep an eye glued to monthly inflation reports.
Alright, now that we've covered the basics, let's dive into the juicy stuff. After all, 99% of businesses feel the pinch from inflation and interest rates—it's the following factors that really matter specifically for Aris.
Beneath the Surface
The first thing I want to dive deeper into is the region where Aris operates: the Permian Basin. Aris relies heavily on this area, as virtually all their revenue originates here. So it makes sense to give this region a closer look.
If you've read Part I, you're already aware that the Permian Basin has some massive strengths from which Aris greatly benefits. Foremost among these strengths are the vast reserves of oil and gas underground, ensuring long-term growth prospects for Aris. Oil and gas production in this region, as illustrated in Figure I below, has been steadily increasing over the years. While production was initially thought to have peaked in the early 1970s, new extraction technologies like hydraulic fracturing (fracking) and horizontal drilling have dramatically boosted production, reshaping both the industry and Aris's potential for future growth.
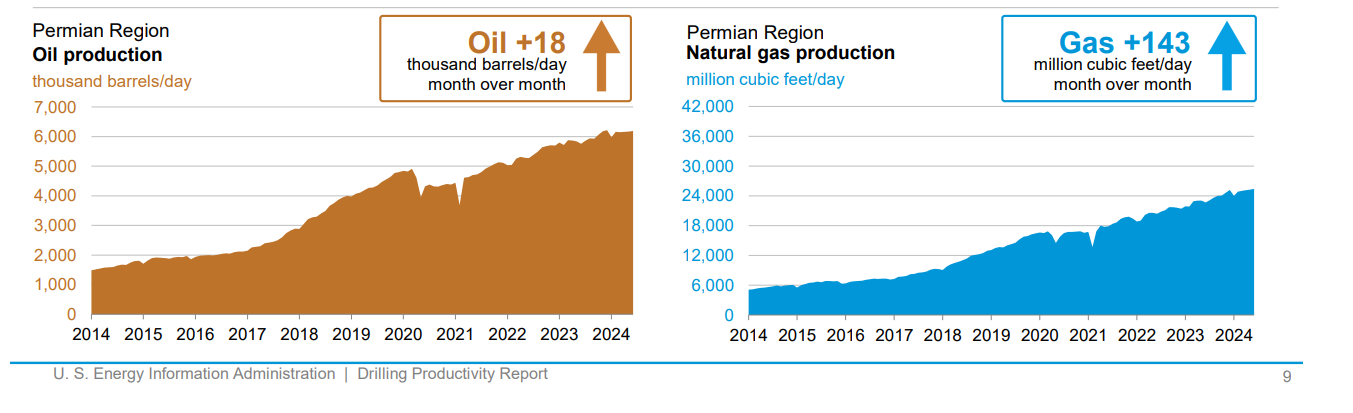
There are no signs of slowing down, given the Permian Basin’s immense reserves. Just the Wolfcamp and Bone Spring formations alone boast estimated proven, technically recoverable reserves of 50 billion barrels of crude oil and nearly 300 trillion cubic feet of natural gas. To put that into perspective, since 1920, the region has produced around 30 billion barrels of oil and 75 trillion cubic feet of natural gas—less in 100 years than what remains today. Factor in ongoing innovations that can make even more oil and gas fields economically viable, and Aris’s future in this region looks exceptionally secure.
The Permian Basin also holds another significant advantage compared to other oil-producing regions in the U.S. As hydraulic fracturing technology advanced, water management needs skyrocketed—from 6.3 million barrels per day in 2017 to 18.9 million barrels per day in 2023. To illustrate this challenge clearly, consider Appalachia, where water production only increased from 0.17 to 0.33 million barrels per day over the same period (Figure II). This striking difference highlights the immense water management challenge faced by the Permian Basin—a challenge that Aris is uniquely positioned and eager to address.

Yet, there are also risks associated with the Permian Basin that investors should keep in mind. For instance, there's a notable shortage of available workforce in the region. In Q4 2024, the average unemployment rate was only 2.9%, indicating a tight labor market. This makes it challenging for businesses, including Aris, to recruit and retain skilled employees.
Climate change also significantly impacts this region, primarily due to the substantial methane emissions resulting from flaring—a process where excess natural gas is burned off during extraction. This practice not only worsens air quality but also contributes to light pollution. Additionally, seismic activity poses another critical concern.
A common industry practice is injecting produced water back into underground formations. Unfortunately, this process significantly increases seismic activity by raising underground pressure, leading to earthquakes. You can imagine local authorities aren't thrilled about this, seamlessly bringing us to our next external factor: regulation.
Drill Baby Drill
Regulation is a crucial factor for Aris, and it will remain so in the future. Initially, I was somewhat apprehensive when I first began researching the company. Coming from Western Europe, I'm accustomed to regulation having a rather poor reputation—often seen as complicating business operations, especially concerning sustainability.
Take the EU’s Corporate Sustainability Reporting Directive, for example, where companies must report on thousands of metrics, often appearing disproportionately burdensome relative to the benefits.
However, my fears about regulation in the Permian Basin quickly proved unwarranted. Sure, Aris faces challenges like seismic activities that occasionally force them to limit or abandon wells. Yet, these very earthquakes have pushed the focus increasingly towards recycling produced water. Over recent years, Aris has heavily invested in recycling produced water, enabling reuse in fracking and potentially other applications in the future. Regulatory trends are increasingly supporting these initiatives, primarily driven by necessity.
Historically, Texas and especially New Mexico—home to the Permian Basin—had limited restrictions on freshwater extraction, resulting in severely depleted aquifers. This situation has forced state governments to become increasingly receptive to utilizing filtered produced water, even for agriculture. Although still evolving, the regulatory landscape in states like New Mexico is progressively favoring filtered produced water for broader uses, including agriculture.
Furthermore, strategic partnerships between Aris and its largest customers highlight this shift. They're collaboratively exploring cost-effective, scalable solutions for treating produced water, making it viable for reuse in sectors like non-consumptive agriculture and alternative energy.
On another note, recent policy developments, especially under the previous Trump administration, temporarily eased regulatory barriers, granting additional permits for new rigs. This has lowered short-term risks, enhancing Aris's prospects for meeting growth expectations. Whether this policy is beneficial in the long term is debatable, but that’s a discussion for another time—we're not a political newsletter, after all.
Still, it's essential to remain cautious. While short-term regulatory easing supports Aris's growth outlook, long-term implications remain uncertain. Additionally, regulatory easing under Trump primarily aimed to lower energy prices, which isn't necessarily favorable for oil and gas producers.
Lower Prices, Lower Production?
This brings us to today's final external factor: oil and gas prices, thanks in part to recent actions by Trump. The theory goes like this: when oil prices drop, producers cut back their production to limit supply, aiming to stabilize or drive prices back up. This strategy helps balance supply and demand, safeguards profitability, and secures long-term investments. Additionally, collaboration within cartels like OPEC plays a crucial role in collectively agreeing to reduce output, preventing excessively sharp price declines. Lower oil prices also render less accessible and costlier oil reserves economically unviable to exploit, prompting producers to wait for prices to rise before tapping these reserves.
Now, I've always been skeptical of textbook theories—real life rarely follows the script perfectly. So, I decided to put this theory to the test. And for once, I was right.
Don't believe me? Just check out the two figures below.

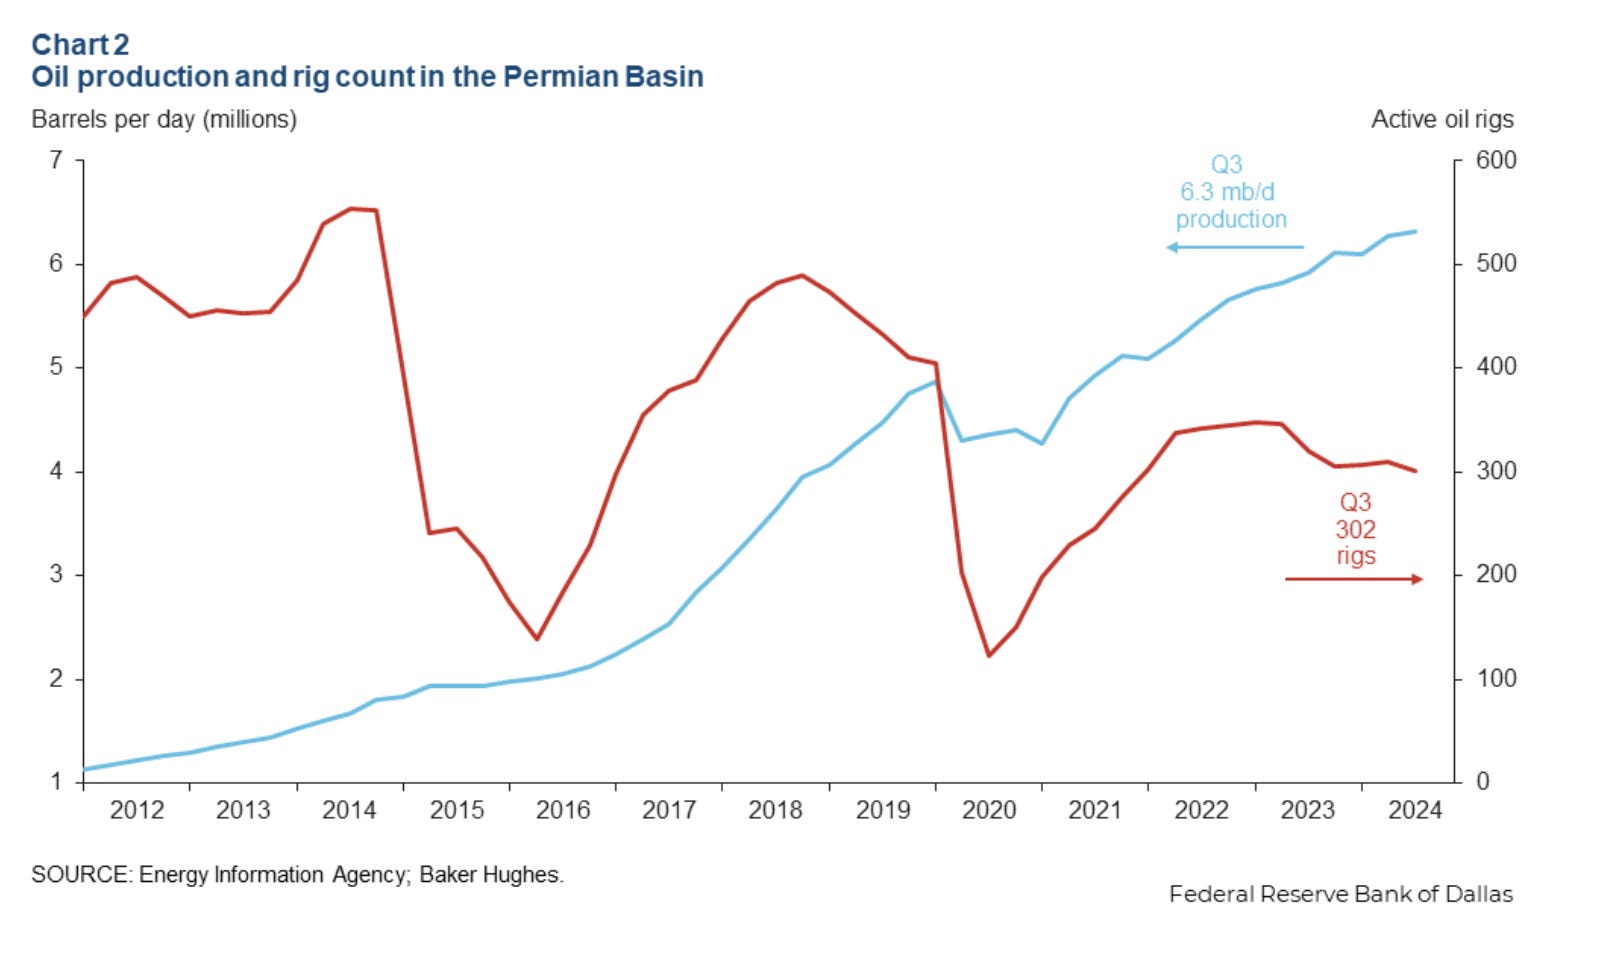
Figure III illustrates oil prices, while Figure IV shows oil production in the Permian Basin over the same period. As you likely already noticed in Figure I, production continues to rise steadily, except for a brief dip during the COVID-19 pandemic. What we do observe, however, is a faster growth in production during periods of rising prices, which makes sense intuitively. Therefore, declining prices slow down potential revenue growth but don't necessarily reduce revenues outright.
The number of active rigs is more directly affected, though. I'm not suggesting there's a perfect one-to-one correlation, but it's clear that rig activity decreases alongside falling prices. This aligns with the economic reality that some rigs become financially unviable at significantly lower prices. Since Aris’s revenues are directly tied to production volumes, lower oil and gas prices inevitably have some impact—albeit limited—on Aris’s profitability.
Closing Remarks
While writing Part I, I quickly realized I'd have to tackle this second part. I think it's the first time I've researched a company so heavily impacted by commodity prices, regulation, and the specific region it operates in. Initially, I saw this as a negative and began questioning if this research was worth pursuing.
Now, I must admit, yes—there are plenty of external influences, but they're not nearly as severe as I initially thought. In the short term, federal deregulation and the easing of restrictions around produced water usage look favorable. However, with Trump, it's always tricky. He's unpredictable and has been known to shift policies abruptly.
Commodity prices also play a role, but they don't appear to threaten Aris's revenues fundamentally. Falling prices tend to slow growth rather than halt revenue entirely—a risk we can certainly manage. If production significantly declined, leading to years of falling revenues, we'd have a bigger problem. While I've deliberately kept specific figures for an upcoming post, I can already share that revenues are trending upward.
The region itself has its challenges. Water scarcity, earthquake risks associated with injecting produced water, and difficulty finding skilled workers are notable hurdles. These challenges are ones Aris needs to manage, but particularly water scarcity and seismic activity also present opportunities, especially for Aris's recycling services. Combined with the vast reserves available, the Permian Basin still holds promising prospects.
My initial fears turned out to be largely unfounded, and I'm happily continuing this deep dive into Aris. Nevertheless, today's analysis highlighted some risks I'll keep in mind moving forward. Next Sunday, we'll dive into Part III, exploring the company's fundamentals, uncovering its strengths and risks, and examining the competitive landscape. Stay tuned, and see you next time!
📢 What about you? What do you think about this external factors? Share your thoughts in the comments—I’d love to hear your take! 👇
🔔 Don’t forget—our deep dive into Aris Water Solutions continues next Sunday. Subscribe now so you don’t miss the next analysis!
Please note: This article includes a disclaimer regarding investment advice.
Our Recent Posts
Should You Sell Your Smartphoto Shares?

Today, we’re not going to talk about Aris – our latest hidden gem, which we found through a top-down analysis. Instead, we’re diving deep into a company that’s close to our hearts (and not just because our portfolio sits in our breast pocket).

Why Aris Might Be the Oil Industry’s Best-Kept Secret

This March, we're diving deep into Aris Water Solutions, a company that made it onto our radar through a top-down analysis.